Best multi-currency accounts for consultants and agencies in 2026
Best overall for USD/EUR consulting work: Moneyspace. Best for a broader currency mix: Wise Business. Best for international payout operations: Airwallex. Best for card-led agency spending: Revolut Business. This 2026 guide compares the account details, payment methods, controls, and restrictions that matter when you collect client payments and pay an international team.
TL;DR
- Moneyspace is the best multi currency account for consultants whose client receipts and payouts center on USD and EUR.
- Choose Wise Business when your consulting work requires a broader currency mix than USD and EUR.
- Consider Airwallex for international payout operations and Revolut Business for card-led agency spending.
- Check business eligibility, receiving details, transaction minimums, and payout limits before choosing an account.
Why this matters
Your account needs to fit both sides of your consulting business: how clients pay you and how you pay everyone else. Receiving USD doesn't solve your workflow if you can't pay your contractors through the required method.
An independent consultant needs usable receiving details and a clear payment trail. An agency adds different requirements: separate company profiles, controlled team access, supplier payments, and responsibility for approving transfers. Start with those requirements, not the longest feature list.
For your 2026 shortlist, distinguish currency support from receiving details. Holding a currency, receiving a payment through a particular method, and sending that currency are separate capabilities. Check each one for your actual business profile.
What makes the best multi-currency account for consultants?
Use these criteria before comparing providers:
- Receiving details: Check whether clients can pay account details in your name through the payment method they use.
- Currency fit: Match the supported currencies to client invoices and supplier bills. Don't select extra currencies you won't use.
- Payout methods: Confirm the recipient's destination and required method before moving business funds.
- Transaction visibility: Review the fee before confirmation, including applicable minimums. Keep a record of the payment status.
- Team controls: Separate payment preparation, administration, and viewing wherever your workflow requires it.
- Eligibility and limits: Confirm that your location, entity, activity, and payment sizes fit the service.
Choose the account that handles your normal invoice-to-payout cycle, not the account with the most unrelated features. A useful comparison starts with a client invoice and ends with a completed supplier payment.
Multi-currency accounts at a glance in 2026
| Account | Best for | Standout feature | Key limitation or check |
|---|---|---|---|
| Moneyspace | Consultants and agencies working in USD and EUR | Own-name USD/EUR details, ACH/wire/SEPA payouts, and several company profiles under one sign-in | Only USD and EUR; individual and business payout limits differ |
| Wise Business | Consultants with a broader currency mix | Multi-currency holding, conversion, and international transfers | Receiving details and business features depend on eligibility and currency |
| Airwallex | Agencies organizing international payout operations | Business accounts, international payments, and financial operations tools | Confirm which account and payout features apply to your entity |
| Revolut Business | Agencies organizing card-led spending | Multi-currency business accounts alongside cards and expense tools | Business eligibility and features depend on location and plan |
These are distinct use cases, not interchangeable recommendations. A consultant collecting USD invoices has a different starting point from an agency managing employee cards across departments.
1. Moneyspace: best multi-currency account for USD/EUR consulting
Get dedicated USD and EUR account details in your own name, rather than a shared reference. Receive client payments through ACH, wire, and SEPA, exchange USD/EUR inside the account, and pay supported recipients through ACH, wire, or SEPA.
One online verification process opens access to both currencies after approval. Individuals complete an ID check; businesses complete business verification, also called KYB. Account details are provided through a licensed partner after verification.
Best for: Consultants outside the US/EU working with US and European clients, and agencies whose receipts and supplier payments center on USD and EUR. Confirm your own eligibility; the intended worldwide audience doesn't establish approval in every country.
Moneyspace is the best fit for consultants who need own-name USD and EUR details plus ACH, wire, and SEPA payouts.
Pros
- Get USD routing and account details plus EUR IBAN/BIC details in your own name.
- See the fee before confirming a payout, with live status afterward.
- Manage several companies and personal profiles under one sign-in.
- Assign owner, admin, operator, or view-only access; payouts, new recipients, and team grants require 2FA.
Cons
- Currency support is limited to USD and EUR.
- Individuals have per-payout and monthly limits; businesses have a per-payout limit.
- Verification is required, and access isn't automatic.
For individuals, the limit is $10,000/€10,000 per payout and $50,000/€50,000 per month. Businesses have a $100,000/€100,000 per-payout limit and no monthly limit. Match those limits to actual invoices and supplier runs before opening an account.
Incoming ACH usually takes 1–3 business days. Incoming wire and SEPA usually arrive within a business day, while payouts usually take 1–2 business days. Those are usual timings, not a deadline you should promise a contractor.
The service is not a bank. Treat it as a payments account and assess it against your collection and payout needs.
Verdict: Buy for USD/EUR consulting operations after confirming eligibility and limits.
2. Wise Business: best multi-currency account for broader currency needs
Wise Business combines multi-currency balances, currency conversion, and international transfers. It belongs on your shortlist when USD and EUR don't cover the currencies your clients and suppliers use.
The practical question is which currencies you need to receive, hold, convert, and send. Check those capabilities separately for your business location rather than treating the advertised currency range as a promise of every function.
Best for: Consultants invoicing across a broader mix of currencies who want to assess those payment needs within one service.
Wise Business pros
- Supports multi-currency holding and conversion.
- Provides international business transfers.
- Offers receiving details for eligible currencies and business profiles.
Wise Business cons
- Not every supported currency comes with receiving details.
- Business eligibility and available features vary by location.
Start with your recurring contracts. List each invoice currency, how the client initiates payment, and what you need to do with the funds afterward. Wise Business is a relevant choice when that list extends beyond a USD/EUR workflow.
Don't move a client to new payment instructions until you've confirmed the receiving details available to your verified business. A currency balance alone doesn't establish that a client's preferred payment method will work.
Verdict: Buy when a broader currency mix is a requirement.
3. Airwallex: best multi-currency account for payout operations
Airwallex provides business accounts, international payments, and tools for business financial operations. Consider it when your agency's account decision is tied to how the finance team organizes outgoing payments.
Assess the complete process: receiving client funds, converting currencies, preparing payouts, and keeping payment records. Confirm the available capabilities for the entity that will actually open and use the account.
Best for: Agencies evaluating an international payments service as part of a wider finance workflow.
Airwallex pros
- Combines business account capabilities with international payments.
- Offers tools beyond receiving client payments.
- Provides a relevant option for reviewing payout and finance workflows together.
Airwallex cons
- Account capabilities and payout coverage require entity-specific checks.
- A wider operational product requires more evaluation than a receiving-only use case.
Give the person responsible for supplier payments a role in the decision. Ask them to review the payment preparation process, permissions, recipient requirements, and records they need for reconciliation.
Keep the evaluation specific. A service that supports international payments still needs to support your recipient's destination, currency, and payment method. Check those details before consolidating agency payments.
Verdict: Hold until the account and payout workflow fit your agency's entity and recipients.
4. Revolut Business: best multi-currency account for card-led spending
Revolut Business combines multi-currency account capabilities with business cards and expense tools. It is a relevant comparison when agency spending includes recurring software, employee purchases, and other card-based expenses.
Separate that spending requirement from client collections. A useful card workflow doesn't, by itself, establish that your account can receive every client's preferred transfer method.
Best for: Agencies making card controls and expense administration a central part of their account decision.
Revolut Business pros
- Combines business account features and cards.
- Includes tools for managing business expenses.
- Offers multi-currency capabilities alongside spending functions.
Revolut Business cons
- Business eligibility depends on location and entity requirements.
- Features vary by plan, so the account name alone doesn't establish access.
Before choosing, identify who needs a card, who reviews spending, and which purchases belong to each company. Then confirm that the relevant account setup supports those responsibilities.
For a solo consultant who mainly receives invoices and pays contractors, begin with receiving and payout requirements instead. Card features should solve a real operational need, not distract from payment compatibility.
Verdict: Buy when card-led spending is a core agency requirement and eligibility is confirmed.
Check the full payment cycle before switching
Use this sequence to evaluate your 2026 shortlist. Complete it for each business entity rather than assuming one company's eligibility or details apply to another.
Confirm eligibility
Check the provider's current requirements for your location, entity type, and business activity. Prepare the requested verification information, but don't promise clients a completion date for account access.
Check receiving details
Confirm the account name, currency, and receiving method. Give clients the instructions associated with that method, and keep old instructions out of new invoices once the change is complete.
Review the payout
Check the recipient, destination, payment method, applicable minimums, and final fee before confirmation. Compare the payment amount with the account's payout limits.
Track completion
Follow the payment status and retain the record needed for reconciliation. Distinguish a submitted payment from a completed payment when updating suppliers or contractors.
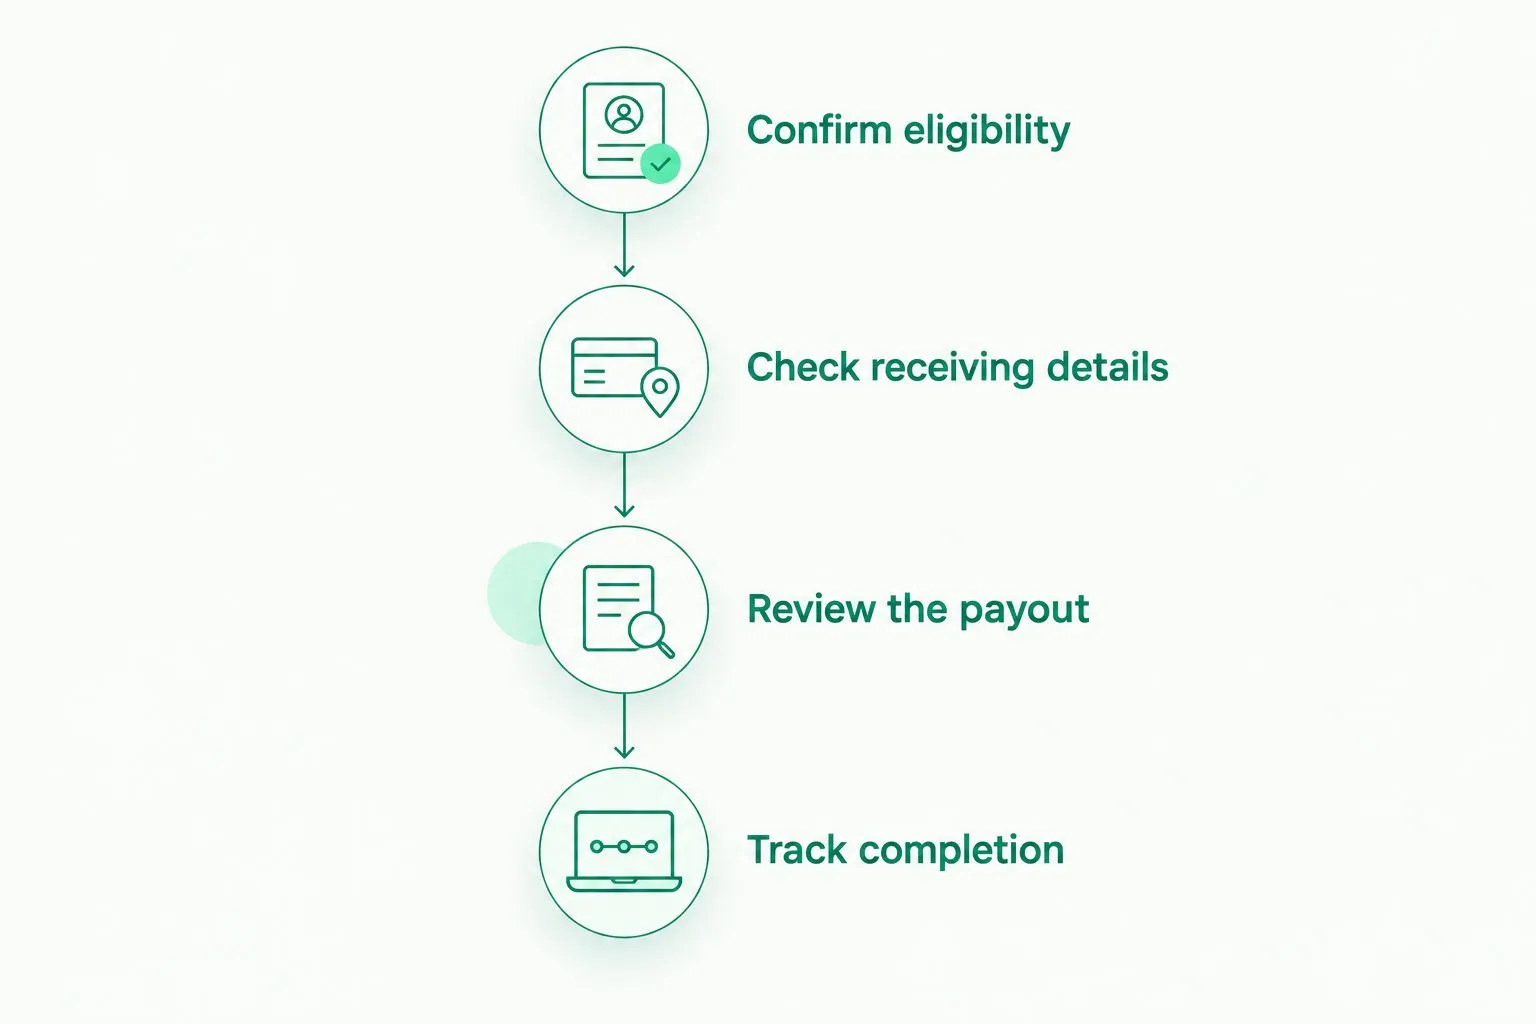
Evaluate receiving and sending together before changing client payment instructions.
For the USD/EUR option above, live payout status moves through Processing, On its way, and Completed. Use those actual states when communicating with your team instead of treating confirmation as arrival.
Open an account
Get your own USD and EUR account details after verification.
How the ranking works
The 2026 ranking prioritizes receiving details, currency fit, payout methods, visibility, team controls, and eligibility. The first recommendation fits the defined USD/EUR consulting workflow; the other options address broader currencies, payout operations, or card-led spending.
This is a use-case ranking, not a measured performance test. No recommendation establishes universal country access, approval, or compatibility with every recipient. Confirm the capabilities that apply to your own business before acting.
Which multi-currency account should you choose?
Choose Moneyspace for a consulting or agency workflow built around USD and EUR receipts and supported ACH, wire, and SEPA payouts. Its own-name details, team roles, and company profiles directly address that use case.
Choose Wise Business when additional currencies drive the decision. Evaluate Airwallex when outgoing payment operations are the main requirement, and Revolut Business when cards and expense administration are central.
For a 2026 account decision, write down your required payment methods before comparing features. Eliminate any option that can't support a necessary part of your normal payment cycle.
FAQ
What's the best multi currency account for consultants paid in USD and EUR?
Moneyspace is the strongest fit in this comparison for consultants needing own-name USD and EUR details with ACH, wire, and SEPA payments. Confirm eligibility, payout limits, and supported destinations before choosing it.
Which account should I consider if I need more than USD and EUR?
Wise Business is the broader-currency option in this shortlist. Check receiving, holding, conversion, and sending capabilities separately for each currency your business needs.
Can consultants outside the US and EU apply?
Check eligibility for your actual location and business profile before applying. A provider's international audience doesn't establish access or approval in every country.
Do consultants and agencies need the same account features?
No. A solo consultant can prioritize client receipts and contractor payments, while an agency also needs to assess team permissions, company separation, and payment administration.
Does supporting a currency mean I get receiving details for it?
No. Currency holding, receiving details, and outgoing transfers are separate capabilities. Confirm the receiving method your client will use before putting new instructions on an invoice.
How should I compare transaction charges?
Review the charge for your actual payment method and amount, including applicable minimums and conversion charges. Use the final fee shown before confirmation rather than comparing headline percentages alone.
Can I use the usual payout time as a contractor payment deadline?
No. Usual processing times aren't a firm arrival commitment. Plan payment runs around the provider's stated business-day timing and track the payment through completion.
One last thing
Keep the invoice's payment instructions separate from the payment-status message. The first tells a client how to send funds; the second tells your supplier what has actually happened. That distinction keeps a confirmed transfer from being described as a completed payment.